Teachers
Certificated staff in CalSTRS who want to know whether the pension alone will cover the life they plan.
California Educators · 403(b) Planning
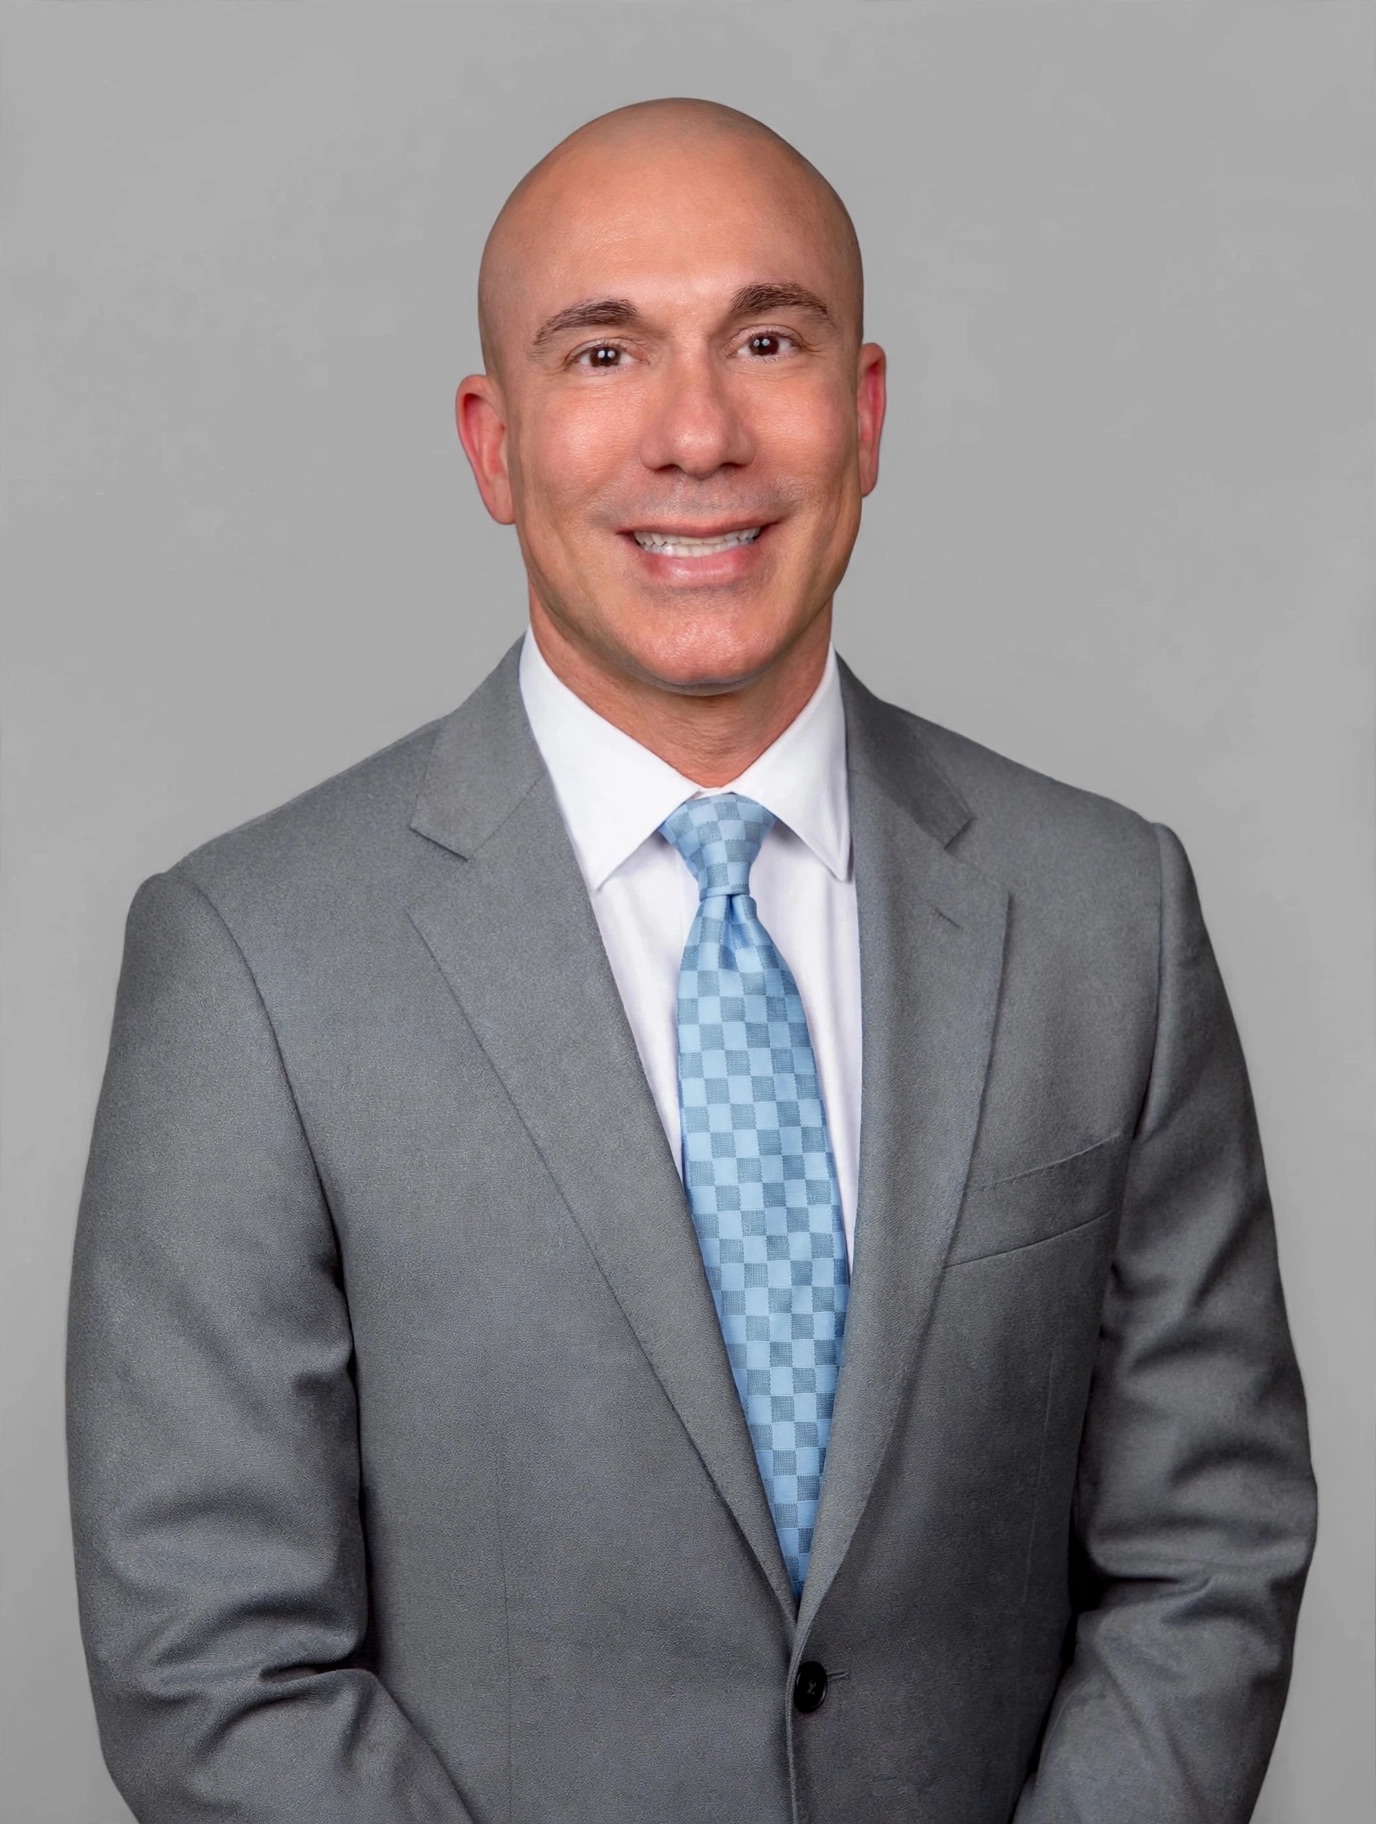
Julio Benenati, Managing Director, Southern California at National Brokers Group, works with teachers and school staff across California. He helps them understand how a 403(b) with fixed indexed annuities can work alongside a CalSTRS or CalPERS pension.
Who we serve
Certificated staff in CalSTRS who want to know whether the pension alone will cover the life they plan.
Office, instructional aide, transportation, nutrition, and maintenance staff, usually in CalPERS.
People in their 50s and 60s who are looking at catch-up contributions and turning savings into income.
Based in Southern California. Consultations for clients anywhere in California are held on Zoom.
The fundamentals
A retirement savings plan for public school employees. Contributions come out of your paycheck and grow tax-deferred until you withdraw them.
$24,500 a year. Age 50 and up may add $8,000. Ages 60–63 may add $11,250 instead. A 15-year service catch-up may apply if your plan allows it. Source: IRS, 2026.
Each district keeps a list of approved 403(b) vendors. The provider you choose shapes your options and costs.
Withdrawals are taxed as ordinary income. Withdrawals before age 59½ may also face an IRS penalty.
Your pension and your 403(b)
| Feature | CalSTRS | CalPERS | 403(b) |
|---|---|---|---|
| Who | Teachers & certificated staff | Classified school staff | Eligible district employees |
| Structure | Defined-benefit pension | Defined-benefit pension | Individual retirement account |
| Participation | Required | Required | Voluntary; you choose the provider |
Your pension is set by a formula. A 403(b) is savings you add on your own, and it can help close the gap between your pension and what you will spend.
For your official pension estimate, see calstrs.com or calpers.ca.gov.
Due diligence
403bCompare.com is California’s official 403(b) comparison site, provided by CalSTRS.
See which vendors your district has approved.
Review fees, returns, and services side by side.
Julio goes through the comparison with you, line by line.
Process
Your pension estimate, your current 403(b), and your timeline.
Fixed indexed annuity options available in your district, including surrender periods, crediting methods, caps, and fees.
If it fits your goals, help with the application and payroll setup. There’s no obligation.
Carriers
Julio offers fixed indexed annuities from these carriers where they’re approved in your district.
Fixed indexed annuities · availability varies by district
Fixed indexed annuities · availability varies by district
Fixed indexed annuities are not securities and do not invest directly in any index. Guarantees are subject to the claims-paying ability of the issuing insurance company. Carrier names are trademarks of their owners.
Planning tool
A quick estimate based on your savings, your monthly spending, and your pension.
This tool is for learning purposes only. It leaves out taxes, inflation, Social Security, and the way returns move up and down over time, so your real experience will differ. Nothing here is a prediction or promise of any outcome, and it does not illustrate or describe any annuity product.
Questions
That depends on the income you’ll want in retirement. A review compares your pension estimate with that goal.
An insurance contract. Interest is credited based in part on how a market index performs, within limits such as caps or participation rates. Your money is not invested in the market or the index. Guarantees are subject to the claims-paying ability of the issuing insurer, and surrender charges may apply.
The consultation is complimentary. If you buy an annuity, Julio is paid a commission by the insurance company, and he’ll explain how that works.
Often, yes, but some contracts have surrender charges. These are reviewed before any change.
Julio is based in Southern California and meets with educators throughout the state by Zoom.
Schedule
Prefer to call? (714) 998-9999 · julio@nationalbrokersgroup.com